Pangaea trades at $8.32 per share and has stayed right on track with the overall market, gaining 10.6% over the last six months. At the same time, the S&P 500 has returned 12.8%.
Is there a buying opportunity in Pangaea, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is Pangaea Not Exciting?
We’re cautious about Pangaea. Here are three reasons we avoid PANL, plus one stock we’d rather own.
1. Low Gross Margin Reveals Weak Structural Profitability
Gross profit margin is a critical metric to track because it sheds light on its pricing power, complexity of products, and ability to procure raw materials, equipment, and labor.
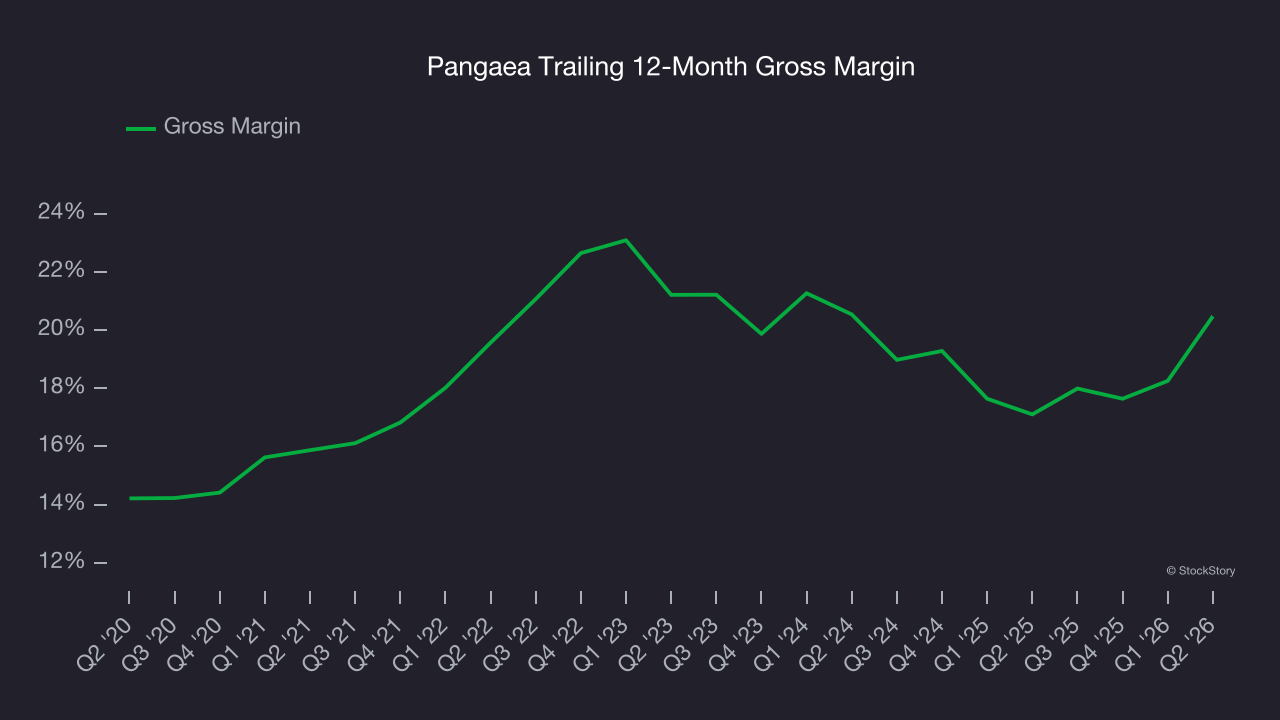
Pangaea has bad unit economics for an industrials business, signaling it operates in a competitive market. As you can see below, it averaged a 19.8% gross margin over the last five years. That means Pangaea paid its suppliers a lot of money ($80.24 for every $100 in revenue) to run its business.
2. Shrinking Operating Margin
Operating margin is one of the best measures of profitability because it tells us how much money a company takes home after procuring and manufacturing its products, marketing and selling those products, and most importantly, keeping them relevant through research and development.
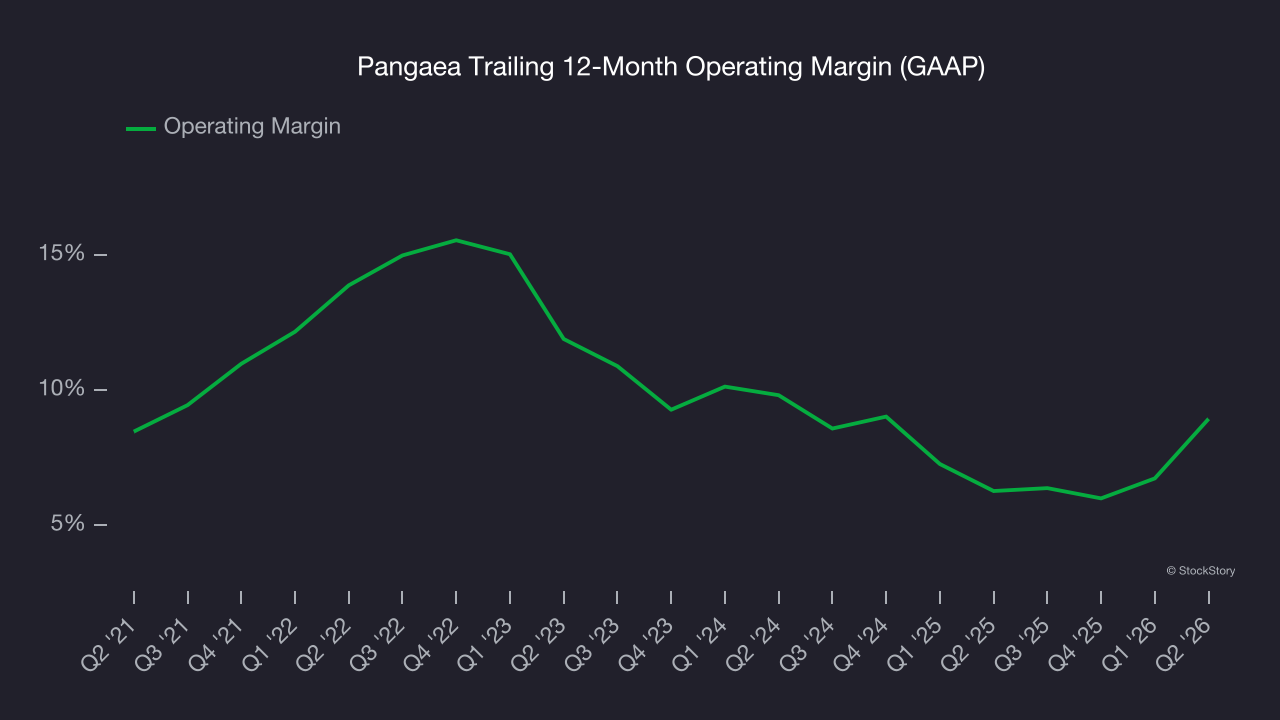
Looking at the trend in its profitability, Pangaea’s operating margin decreased by 4.9 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its operating margin for the trailing 12 months was 8.9%.
3. EPS Trending Down
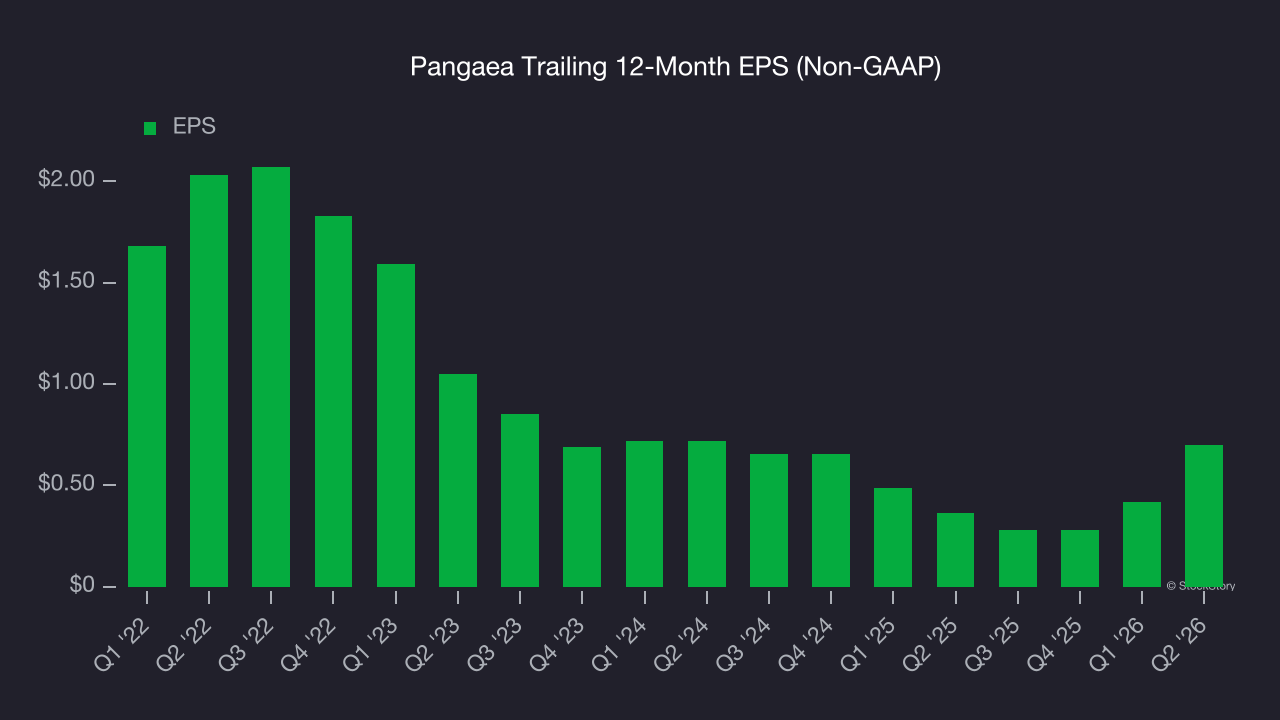
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Pangaea’s full-year EPS dropped 132%, or 23.4% annually, over the last four years. We tend to steer our readers away from companies with falling revenue and EPS, where diminishing earnings could imply changing secular trends and preferences. If the tide turns unexpectedly, Pangaea’s low margin of safety could leave its stock price susceptible to large downswings.
Final Judgment
Pangaea’s business quality ultimately falls short of our standards. That said, the stock currently trades at 9.6× forward P/E (or $8.32 per share). While this valuation is optically cheap, the potential downside is big given its shaky fundamentals. We’re pretty confident there are superior stocks to buy right now. Let us point you toward a safe-and-steady industrials business benefiting from an upgrade cycle.
Stocks We Like More Than Pangaea
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.