
Over the past six months, Leonardo DRS’s shares (currently trading at $35.67) have posted a disappointing 19.4% loss, well below the S&P 500’s 7.7% gain. This may have investors wondering how to approach the situation.
Following the pullback, is now a good time to buy DRS? Find out in our full research report, it’s free.
Why Does DRS Stock Spark Debate?
Developing submarine detection systems for the U.S. Navy, Leonardo DRS (NASDAQ:DRS) is a provider of defense systems, electronics, and military support services.
Two Positive Attributes:
1. Skyrocketing Revenue Shows Strong Momentum
We at StockStory place the most emphasis on long-term growth, but within industrials, a stretched historical view may miss cycles, industry trends, or a company capitalizing on catalysts such as a new contract win or a successful product line. Leonardo DRS’s annualized revenue growth of 10.9% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 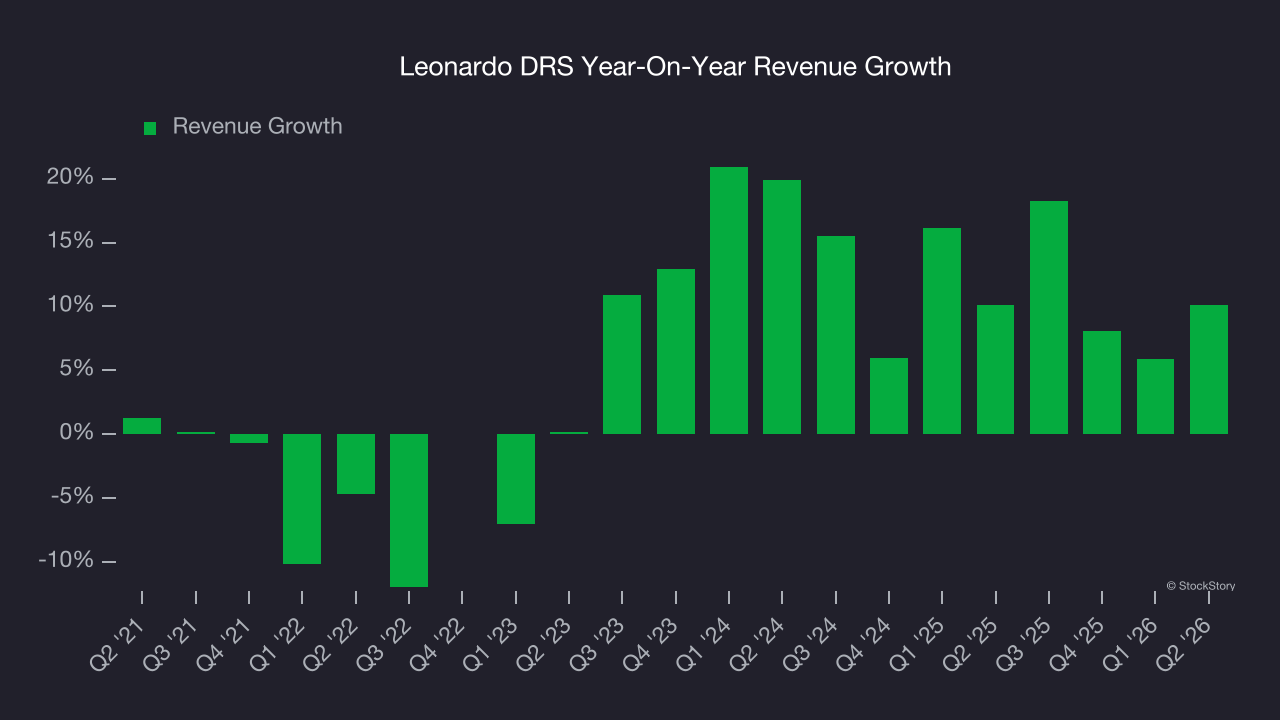
2. Increasing Free Cash Flow Margin Juices Financials
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
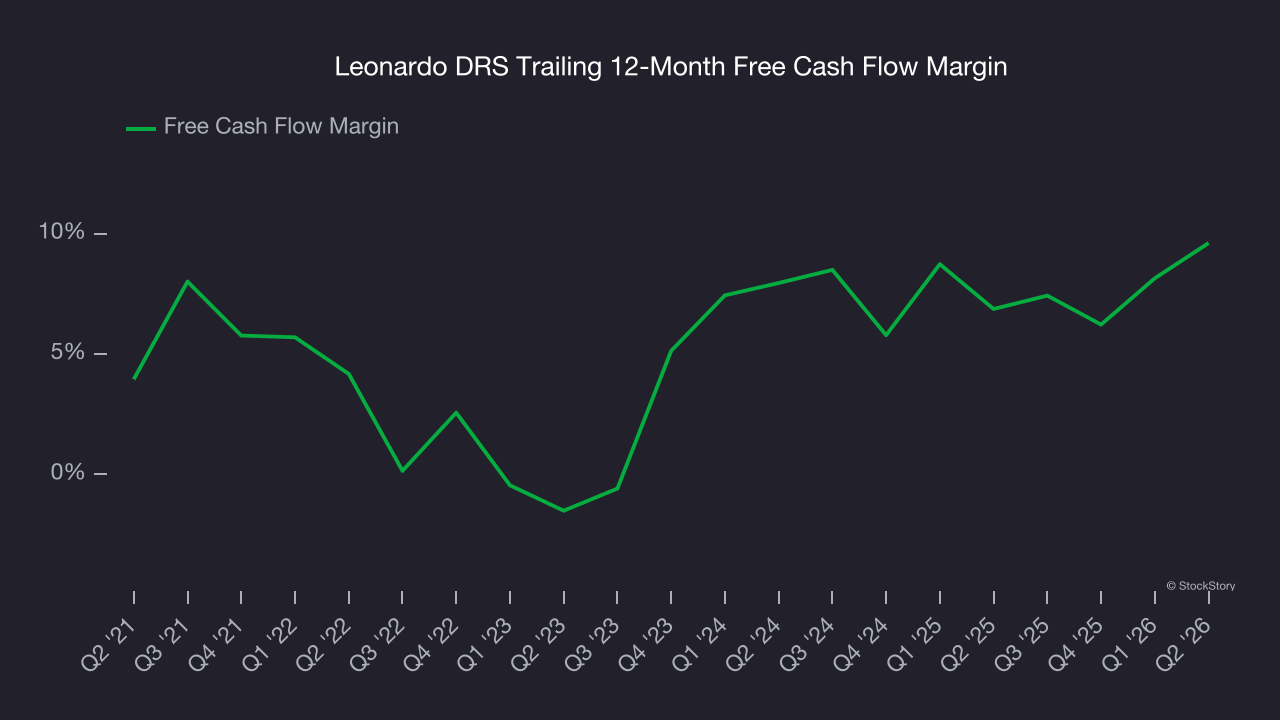
As you can see below, Leonardo DRS’s margin expanded by 5.4 percentage points over the last five years. The company’s improvement shows it’s heading in the right direction, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability. Leonardo DRS’s free cash flow margin for the trailing 12 months was 9.6%.
One Reason to Be Careful:
Backlog Declines as Orders Drop
We can better understand Defense Contractors companies by analyzing their backlog. This metric shows the value of outstanding orders that have not yet been executed or delivered, giving visibility into Leonardo DRS’s future revenue streams.
Leonardo DRS’s backlog came in at $5.09 billion in the latest quarter, and it averaged 6.8% year-on-year declines over the last two years. This performance was underwhelming and shows the company is not winning new orders. It also suggests there may be increasing competition or market saturation. 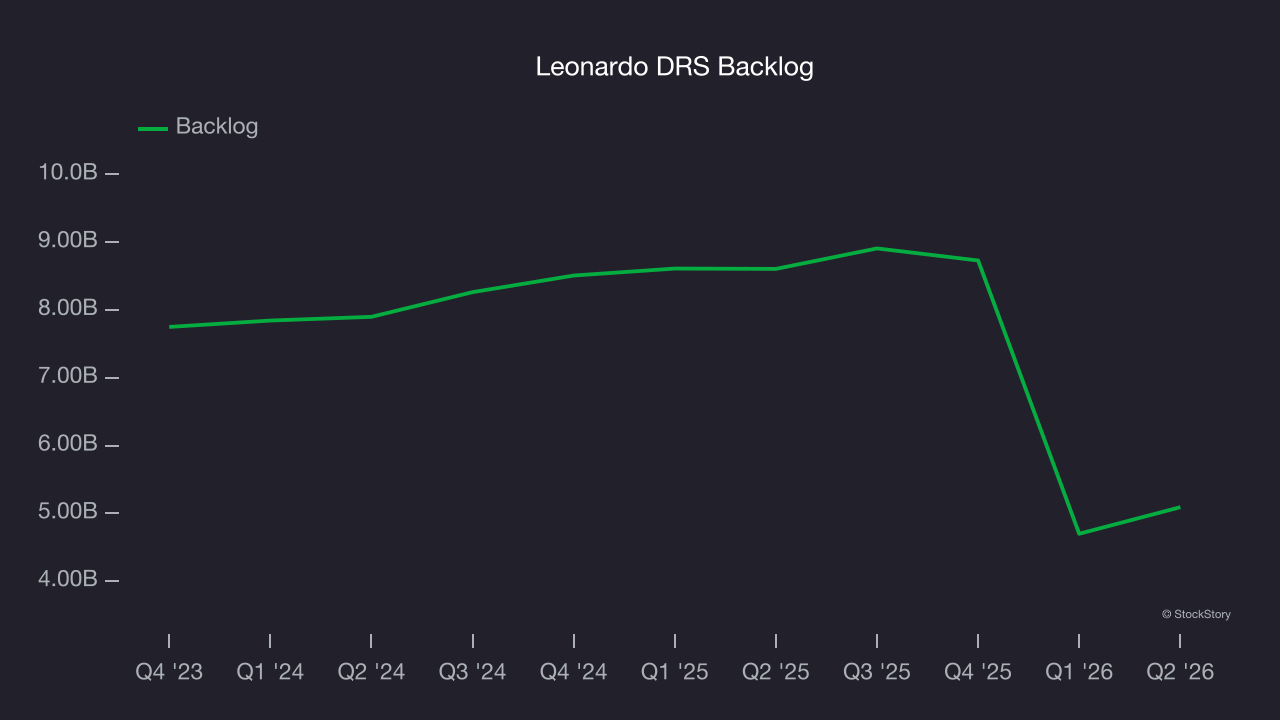
Final Judgment
Leonardo DRS’s positive characteristics outweigh the negatives. After the recent drawdown, the stock trades at 26.2× forward P/E (or $35.67 per share). Is now a good time to initiate a position? See for yourself in our in-depth research report, it’s free.
Stocks We Like Even More Than Leonardo DRS
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.