
Over the past six months, Nelnet’s shares (currently trading at $125.12) have posted a disappointing 9.8% loss, well below the S&P 500’s 7.7% gain. This was partly due to its softer quarterly results and might have investors contemplating their next move.
Is now the time to buy Nelnet, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is Nelnet Not Exciting?
Even though the stock has become cheaper, we’re passing on Nelnet for now. Here are three reasons why there are better opportunities than NNI, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
A company’s long-term sales performance can indicate its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years.
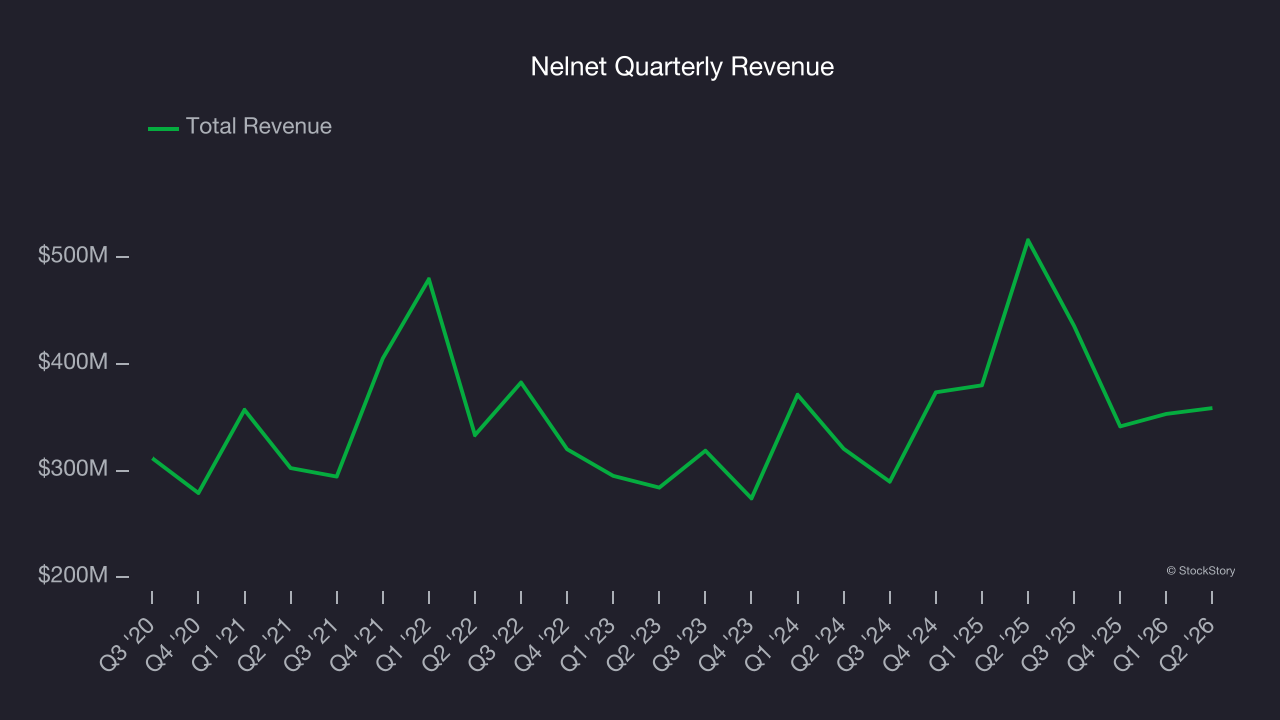
Over the last five years, Nelnet grew its revenue at a sluggish 3.6% compounded annual growth rate. This was below our standard for the financials sector.
2. EPS Trending Down
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
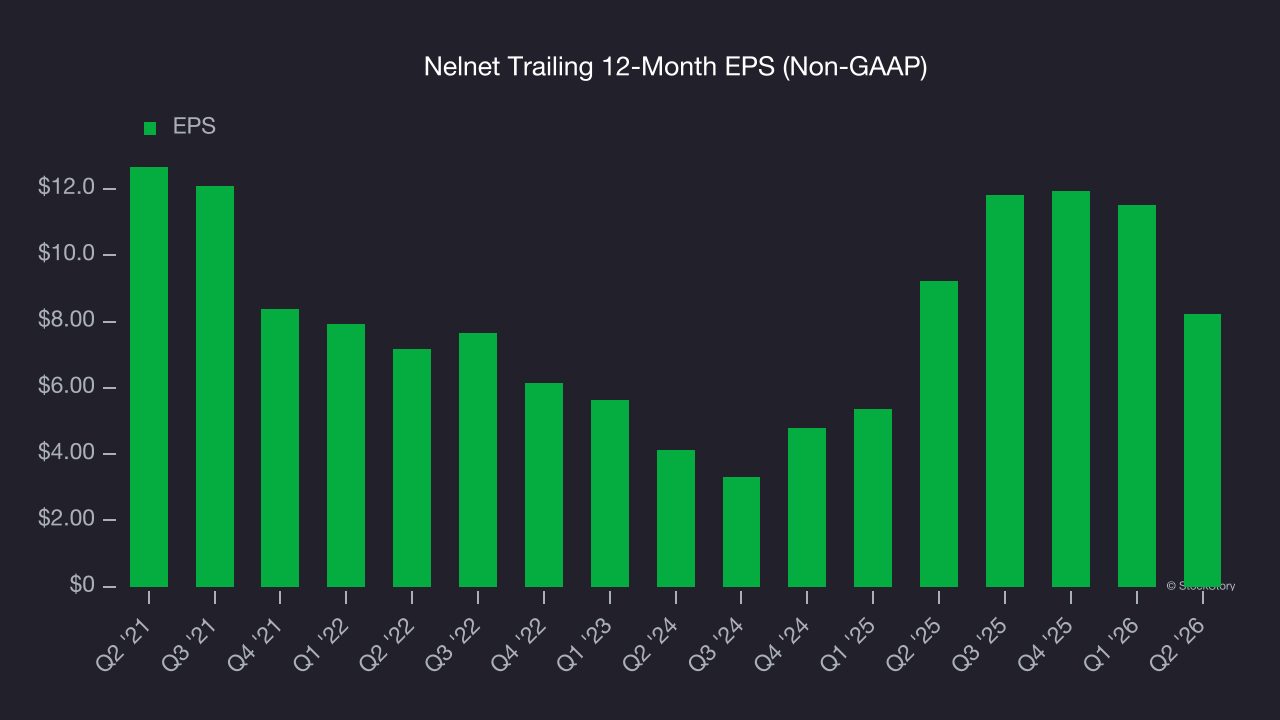
Sadly for Nelnet, its EPS declined by 8.3% annually over the last five years while its revenue grew by 3.6%. This tells us the company became less profitable on a per-share basis as it expanded.
3. High Debt Levels Increase Risk
Nelnet reported $966.3 million of cash and $7.04 billion of debt on its balance sheet in the most recent quarter.
As investors in high-quality companies, we primarily focus on whether a company’s profits can support its debt.
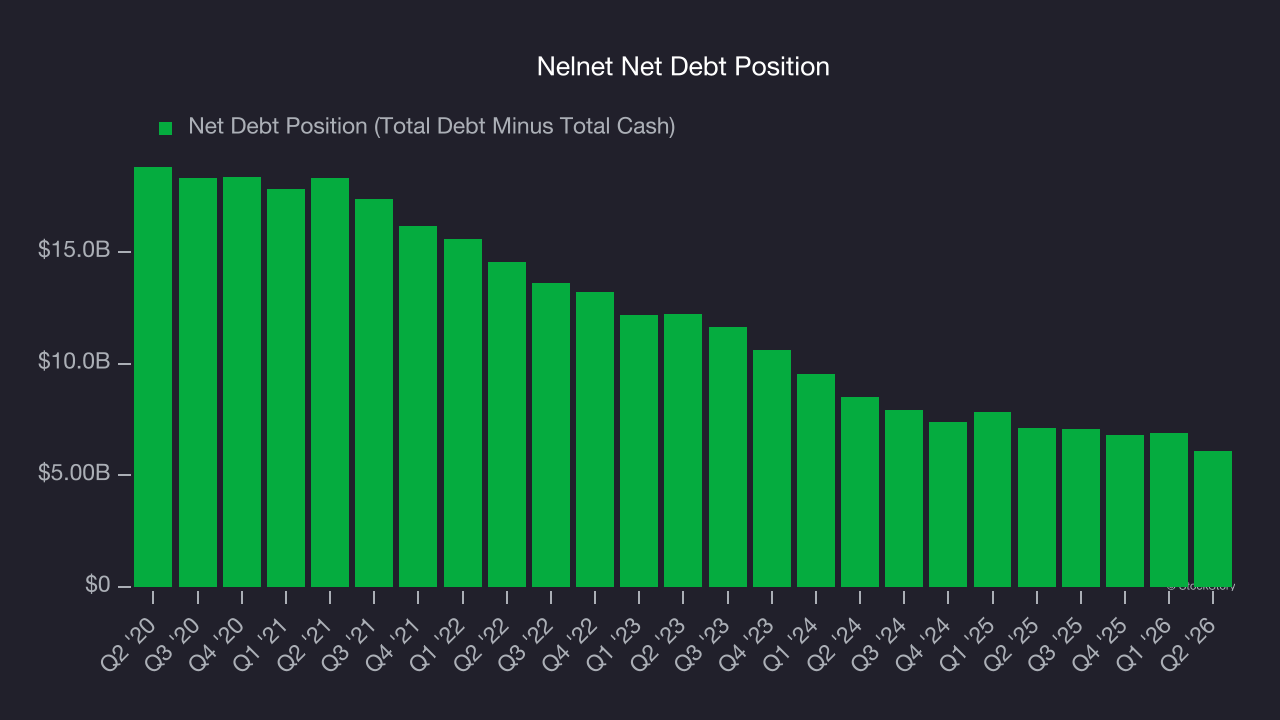
With $355.1 million of EBITDA over the last 12 months, we view Nelnet’s 17.1× net-debt-to-EBITDA ratio as inadequate. The company’s lacking profits relative to its borrowings give it little breathing room, raising red flags.
Final Judgment
Nelnet isn’t a terrible business, but it isn’t one of our picks. After the recent drawdown, the stock trades at 15.4× forward P/E (or $125.12 per share). This valuation tells us it’s a bit of a market darling with a lot of good news priced in - we think there are better opportunities elsewhere. We’d suggest looking at one of Charlie Munger’s all-time favorite businesses.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.