
What a brutal six months it’s been for Sunrun. The stock has dropped 35.3% and now trades at $7.62, rattling many shareholders. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Sunrun, or does it present a risk to your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Is Sunrun Not Exciting?
Even with the cheaper entry price, we don’t have much confidence in Sunrun. Here are three reasons you should be careful with RUN, plus one stock we’d rather own.
1. Operating Losses Sound the Alarm
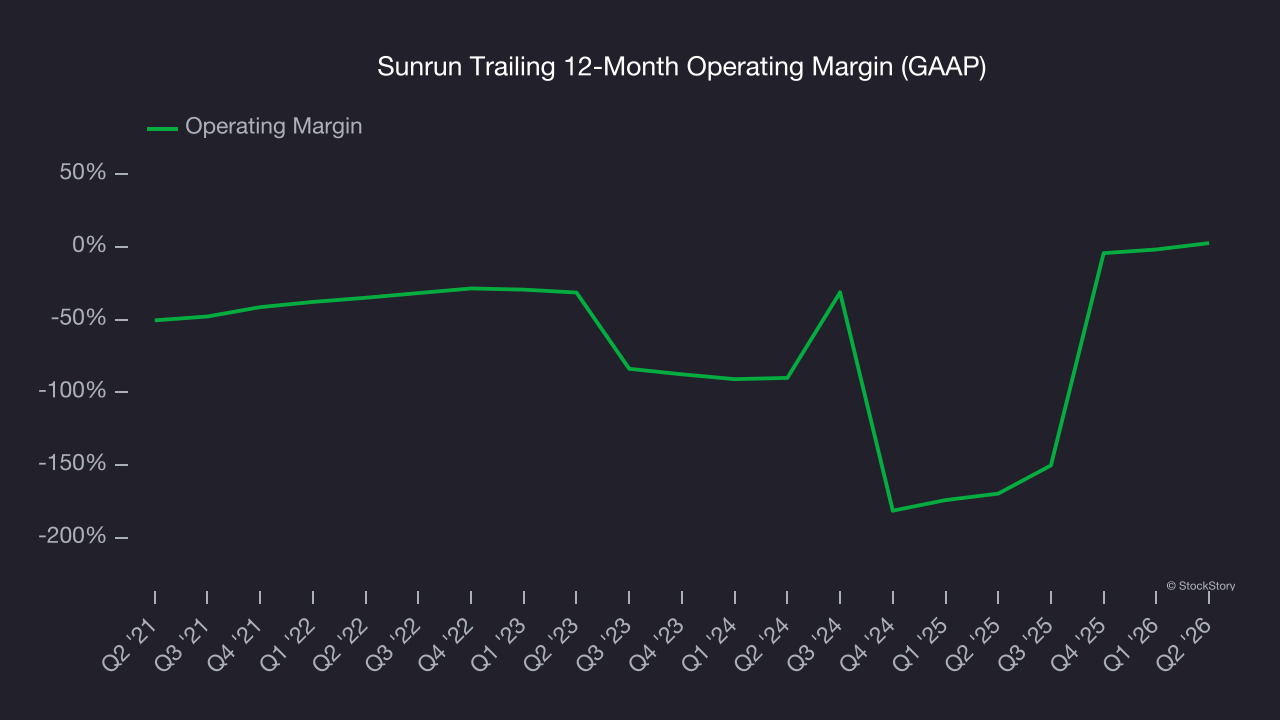
Operating margin is one of the best measures of profitability because it tells us how much money a company takes home after procuring and manufacturing its products, marketing and selling those products, and most importantly, keeping them relevant through research and development.
Although Sunrun was profitable this quarter from an operational perspective, it’s generally struggled over a longer time period. Its expensive cost structure has contributed to an average operating margin of negative 56.6% over the last five years. Unprofitable industrials companies require extra attention because they could get caught swimming naked when the tide goes out. It’s hard to trust that the business can endure a full cycle.
2. Cash Burn Ignites Concerns
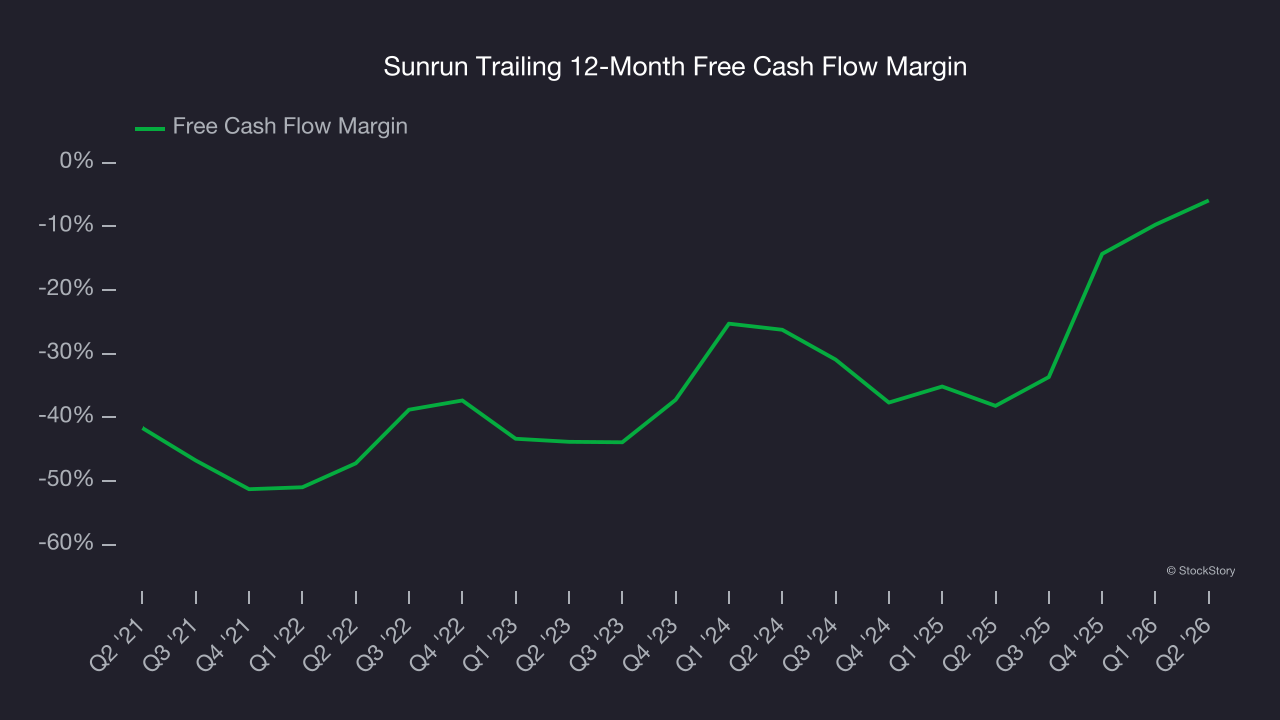
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Sunrun’s demanding reinvestments have drained its resources over the last five years, putting it in a pinch and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 29.4%, meaning it lit $29.43 of cash on fire for every $100 in revenue.
3. High Debt Levels Increase Risk
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
Sunrun’s $15.21 billion of debt exceeds the $1.14 billion of cash on its balance sheet. Furthermore, its 17× net-debt-to-EBITDA ratio (based on its EBITDA of $840.6 million over the last 12 months) shows the company is overleveraged.
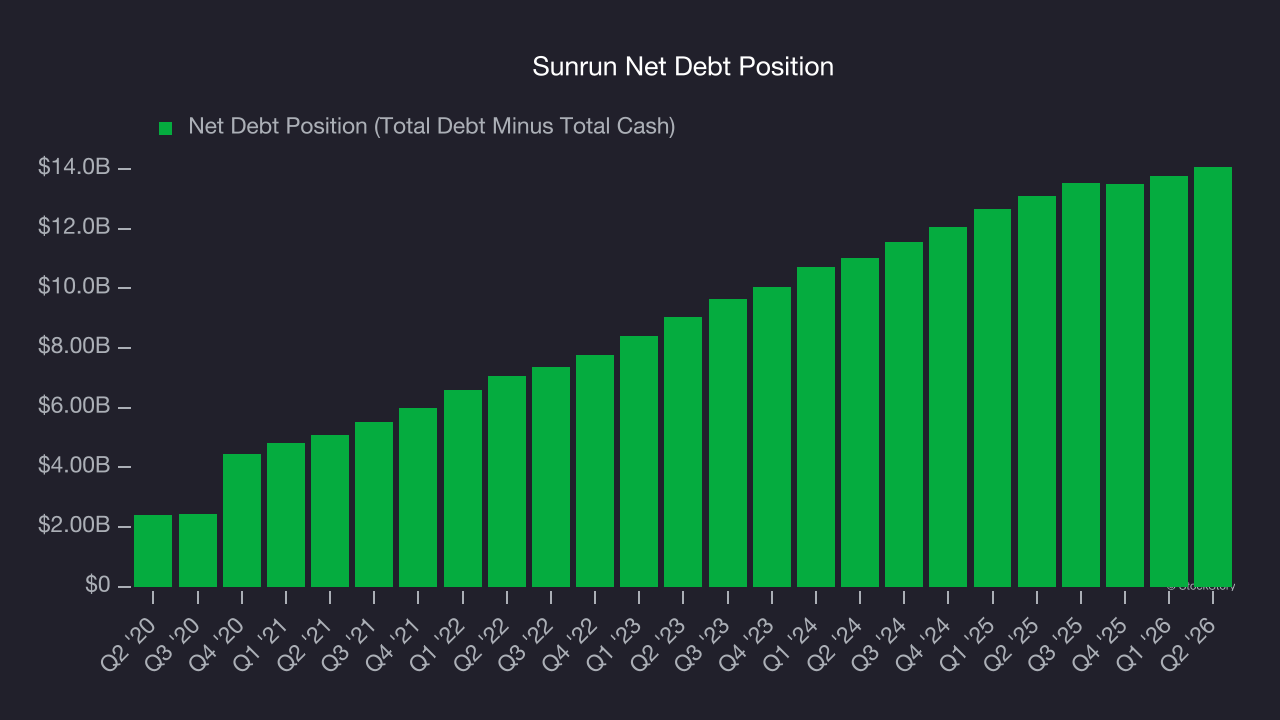
At this level of debt, incremental borrowing becomes increasingly expensive and credit agencies could downgrade the company’s rating if profitability falls. Sunrun could also be backed into a corner if the market turns unexpectedly – a situation we seek to avoid as investors in high-quality companies.
We hope Sunrun can improve its balance sheet and remain cautious until it increases its profitability or pays down its debt.
Final Judgment
Sunrun isn’t a terrible business, but it isn’t one of our picks. Following the recent decline, the stock trades at 9.2× forward P/E (or $7.62 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re fairly confident there are better investments elsewhere. Let us point you toward one of our top software and edge computing picks.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.