
What a brutal six months it’s been for Atlas Energy Solutions. The stock has dropped 36.1% and now trades at $9.36, rattling many shareholders. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Atlas Energy Solutions, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Do We Think Atlas Energy Solutions Will Underperform?
Even with the cheaper entry price, we’re passing on Atlas Energy Solutions for now. Here are three reasons you should be careful with AESI, plus one stock we’d rather own.
1. Shrinking EBITDA Margin
Adjusted EBITDA margin captures the true operating profitability of an energy producer by removing accounting noise around depletion and capitalized drilling costs. It reveals how much cash the asset base generates before capital structure and reinvestment requirements shape reported earnings.
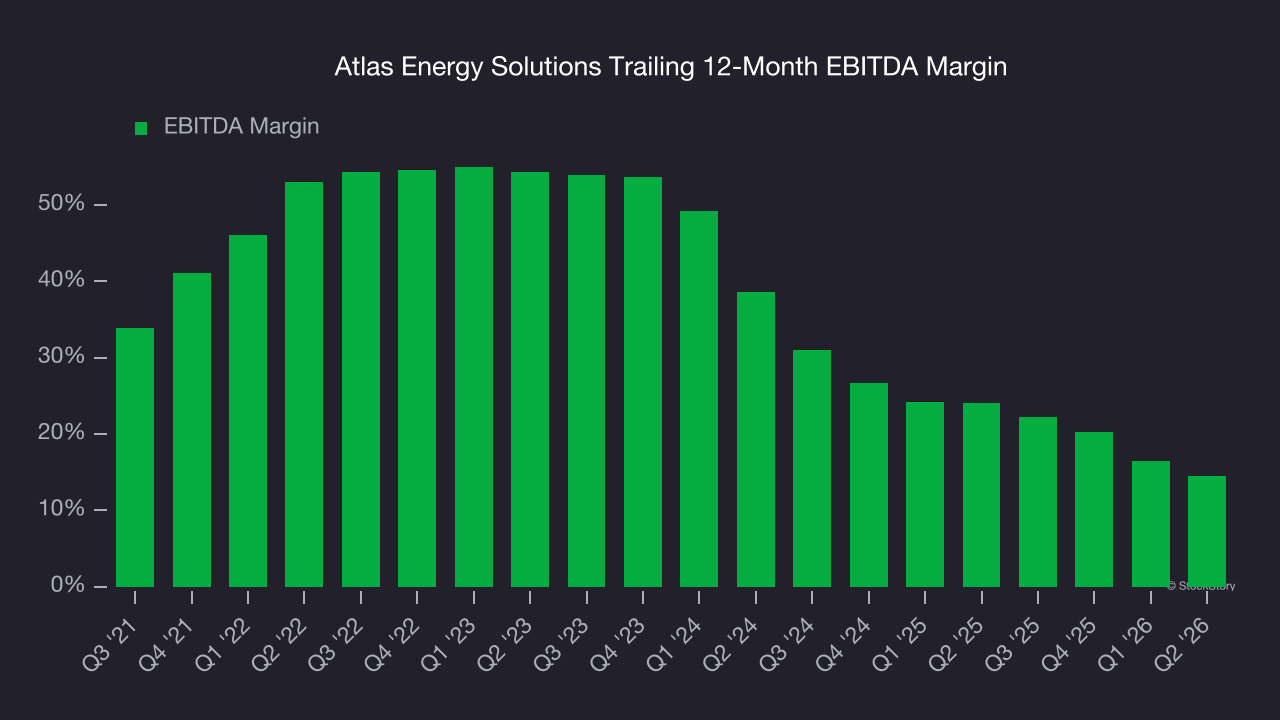
Looking at the trend in its profitability, Atlas Energy Solutions’s EBITDA margin decreased by 38.5 percentage points over the last year. Atlas Energy Solutions’s performance was poor no matter how you look at it - it shows that costs were rising and it couldn’t pass them onto its customers. Its EBITDA margin for the trailing 12 months was 14.5%.
2. Cash Burn Ignites Concerns
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
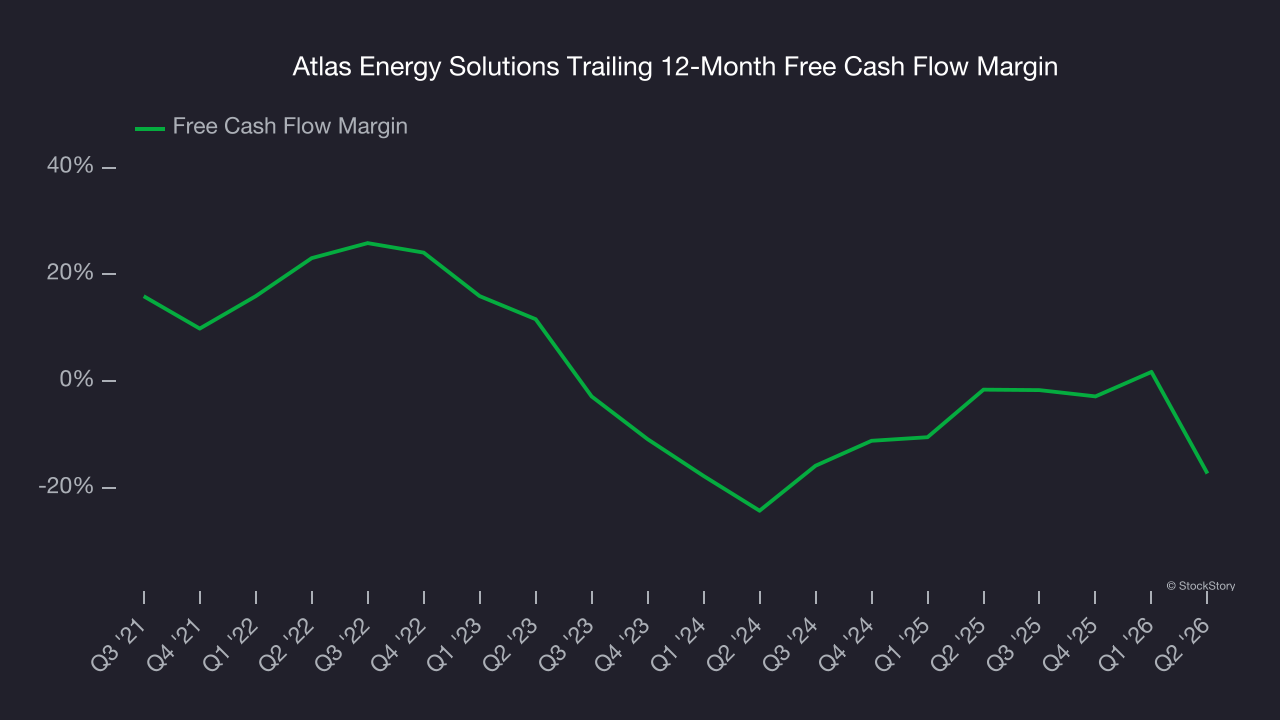
Atlas Energy Solutions’s demanding reinvestments have drained its resources over the last five years, putting it in a pinch and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 6.5%, meaning it lit $6.51 of cash on fire for every $100 in revenue.
3. Short Cash Runway Exposes Shareholders to Potential Dilution
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
Atlas Energy Solutions burned through $184.1 million of cash over the last year, and its $966.7 million of debt exceeds the $168.2 million of cash on its balance sheet. This is a deal breaker for us because indebted loss-making companies spell trouble.
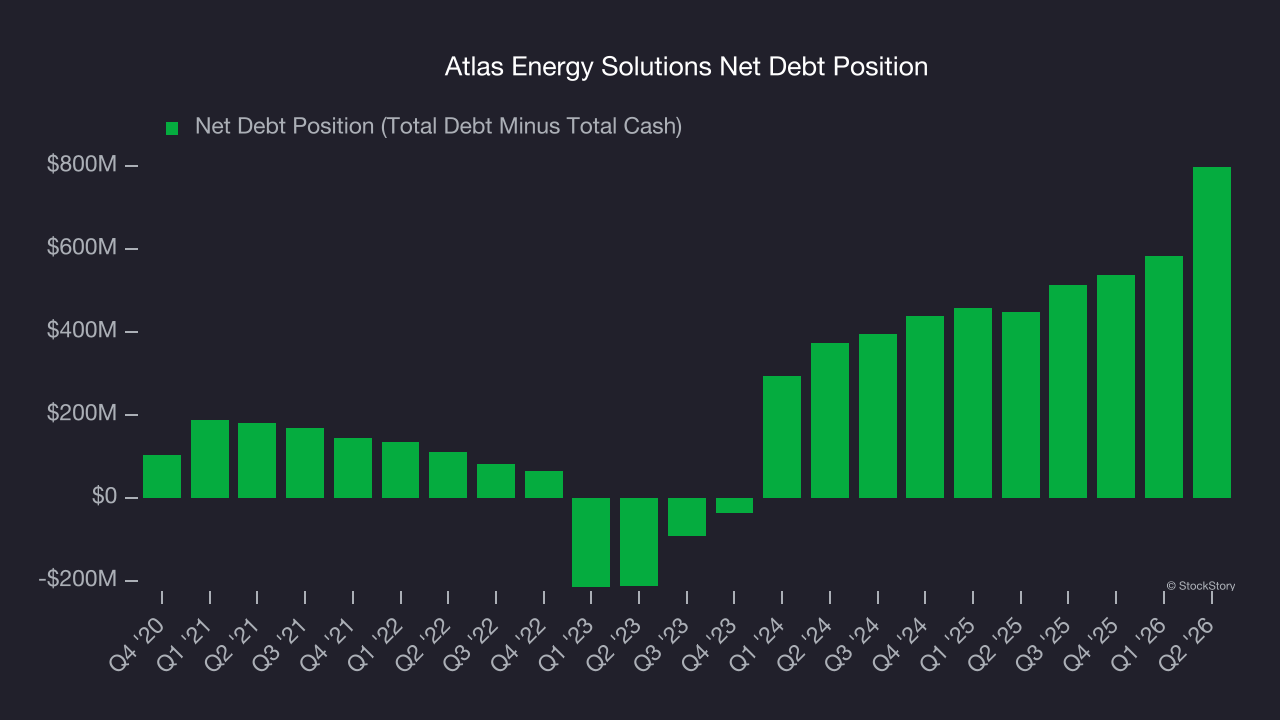
Unless the Atlas Energy Solutions’s fundamentals change quickly, it might find itself in a position where it must raise capital from investors to continue operating. Whether that would be favorable is unclear because dilution is a headwind for shareholder returns.
We remain cautious of Atlas Energy Solutions until it generates consistent free cash flow or any of its announced financing plans materialize on its balance sheet.
Final Judgment
Atlas Energy Solutions falls short of our quality standards. Following the recent decline, the stock trades at 9.1× forward EV-to-EBITDA (or $9.36 per share). This valuation is reasonable, but the company’s shaky fundamentals present too much downside risk. There are superior stocks to buy right now. We’d recommend looking at one of our all-time favorite software stocks.
Stocks We Like More Than Atlas Energy Solutions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.