
Over the last six months, Toll Brothers’s shares have sunk to $133.28, producing a disappointing 10.1% loss - a stark contrast to the S&P 500’s 8.9% gain. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Toll Brothers, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Toll Brothers Not Exciting?
Even with the cheaper entry price, we don’t have much confidence in Toll Brothers. Here are three reasons why there are better opportunities than TOL, plus one stock we’d rather own.
1. Backlog Declines as Orders Drop
In addition to reported revenue, backlog is a useful data point for analyzing Home Builders companies. This metric shows the value of outstanding orders that have not yet been executed or delivered, giving visibility into Toll Brothers’s future revenue streams.
Toll Brothers’s backlog came in at $6.24 billion in the latest quarter, and it averaged 8.1% year-on-year declines over the last two years. This performance was underwhelming and shows the company is not winning new orders. It also suggests there may be increasing competition or market saturation. 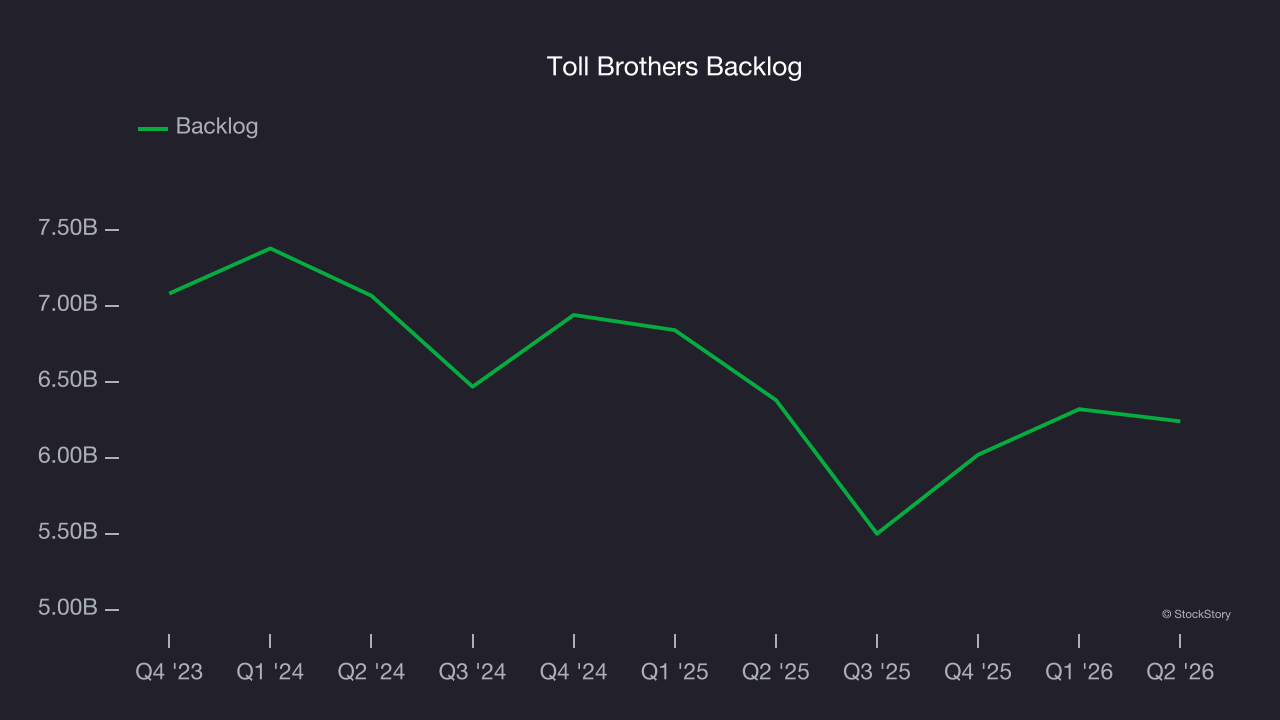
2. Projected Revenue Growth Shows Limited Upside
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Toll Brothers’s revenue to stall, close to its 5.3% annualized growth for the past five years. This projection is underwhelming and indicates its newer products and services will not catalyze better top-line performance yet.
3. EPS Took a Dip Over the Last Two Years
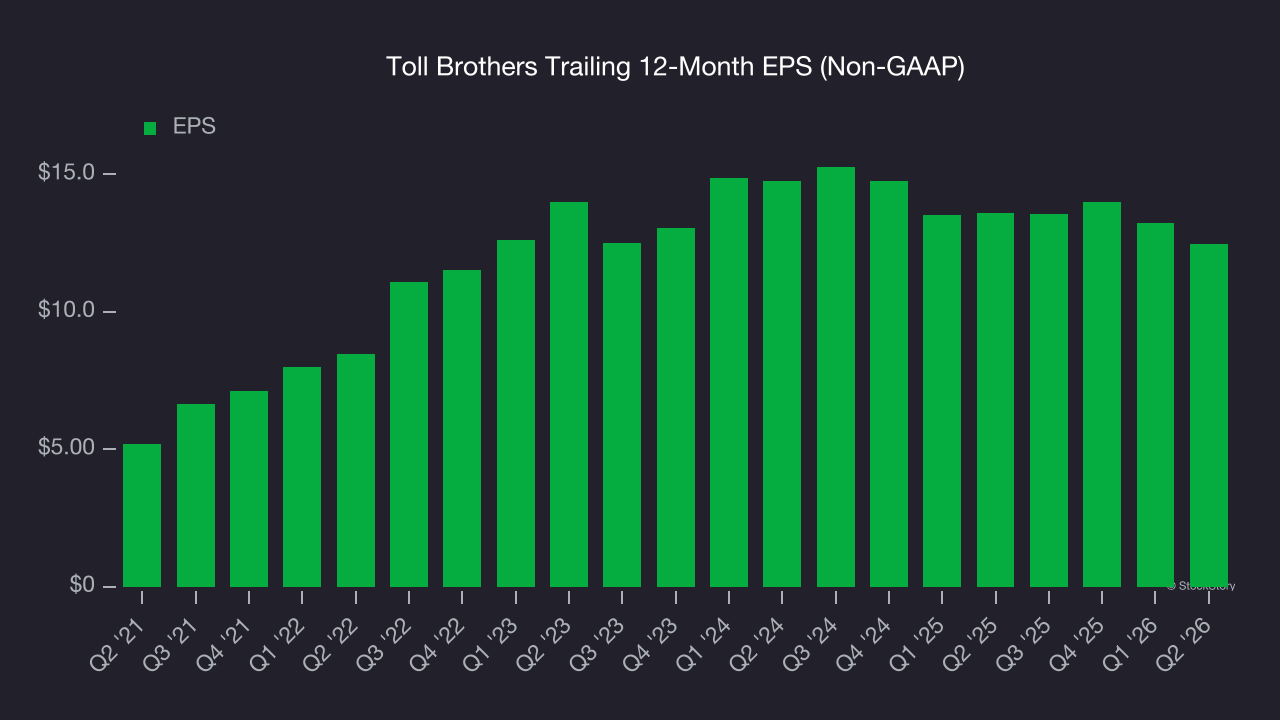
Although long-term earnings trends give us the big picture, we like to analyze EPS over a shorter period to see if we are missing a change in the business.
Sadly for Toll Brothers, its EPS declined by 8.1% annually over the last two years while its revenue grew by 1.1%. This tells us the company became less profitable on a per-share basis as it expanded.
Final Judgment
Toll Brothers isn’t a terrible business, but it isn’t one of our picks. After the recent drawdown, the stock trades at 9.8× forward P/E (or $133.28 per share). While this valuation is optically cheap, the potential downside is big given its shaky fundamentals. We’re fairly confident there are better investments elsewhere. We’d recommend looking at the most dominant software business in the world.
Stocks We Would Buy Instead of Toll Brothers
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.