
Packaged foods company Conagra Brands (NYSE:CAG) met Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q1 2027), but sales fell by 1.4% year on year to $2.60 billion. Its non-GAAP profit of $0.41 per share was 45.7% above analysts’ consensus estimates.
Is now the time to buy Conagra? Find out by accessing our full research report, it’s free.
Conagra (CAG) Q3 CY2026 Highlights:
- Revenue: $2.60 billion vs analyst estimates of $2.59 billion (1.4% year-on-year decline, in line)
- Adjusted EPS: $0.41 vs analyst estimates of $0.28 (45.7% beat)
- Adjusted EBITDA: $451.4 million vs analyst estimates of $345.8 million (17.4% margin, 30.5% beat)
- Management reiterated its full-year Adjusted EPS guidance of $1.45 at the midpoint
- Operating Margin: 10.3%, down from 13.2% in the same quarter last year
- Free Cash Flow was -$127.9 million compared to -$26.2 million in the same quarter last year
- Organic Revenue fell 1.1% year on year (beat)
- Sales Volumes fell 2.1% year on year, in line with the same quarter last year
- Market Capitalization: $6.76 billion
CEO PerspectiveJohn Brase, president and chief executive officer of Conagra Brands, commented, "We delivered a solid start to fiscal 2027 with top line results largely in line with expectations and profit ahead of expectations amid a challenging operating environment. Importantly, we are acting on our previously outlined priorities including restoring margins, increasing investment, reducing complexity, and rebalancing capital allocation, which are translating into measurable progress across the business. While there is more work to be done, we remain on track to deliver the year and are reaffirming our fiscal 2027 guidance."
Company Overview
Founded in 1919 as Nebraska Consolidated Mills in Omaha, Nebraska, Conagra Brands today (NYSE:CAG) boasts a diverse portfolio of packaged foods brands that includes everything from whipped cream to jarred pickles to frozen meals.
Revenue Growth
A company’s long-term sales performance is one signal of its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years.
With $11.24 billion in revenue over the past 12 months, Conagra is one of the larger consumer staples companies and benefits from a well-known brand that influences purchasing decisions. However, its scale is a double-edged sword because it’s harder to find incremental growth when your existing brands have penetrated most of the market. To accelerate sales, Conagra likely needs to optimize its pricing or lean into new products and international expansion.
As you can see below, Conagra struggled to generate demand over the last three years. Its sales dropped by 2.9% annually as consumers bought less of its products.
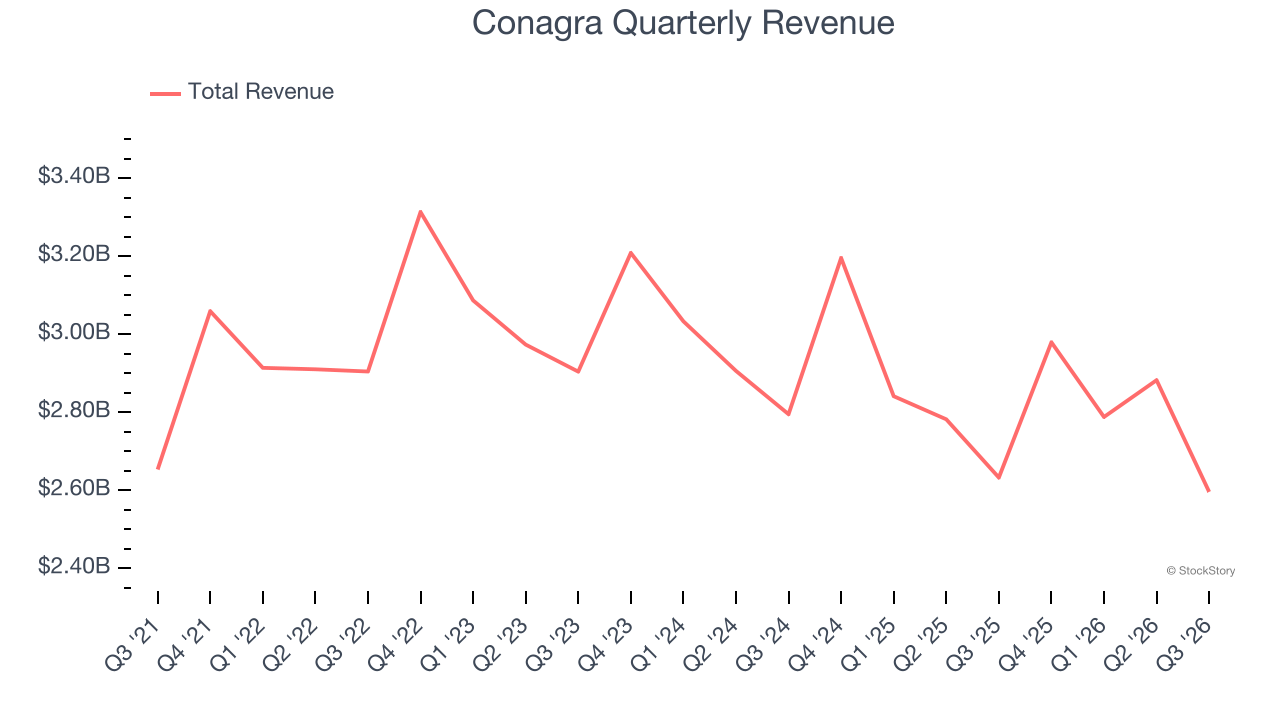
This quarter, Conagra reported a rather uninspiring 1.4% year-on-year revenue decline to $2.60 billion of revenue, in line with Wall Street’s estimates.
Looking ahead, sell-side analysts expect revenue to decline by 3.8% over the next 12 months, similar to its three-year rate. This projection doesn’t excite us and implies its newer products will not accelerate its top-line performance yet.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Volume Growth
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is the lifeblood of a successful staples business as there’s a ceiling to what consumers will pay for everyday goods; they can always trade down to non-branded products if the branded versions are too expensive.
To analyze whether Conagra generated its growth (or lack thereof) from changes in price or volume, we can compare its volume growth to its organic revenue growth, which excludes non-fundamental impacts on company financials like mergers and currency fluctuations.
Over the last two years, Conagra’s average quarterly volumes have shrunk by 1.6%. This isn’t ideal for a consumer staples company, where demand is typically stable. In the context of its 1.4% average organic sales declines, we can see that most of the company’s losses have come from fewer customers purchasing its products.
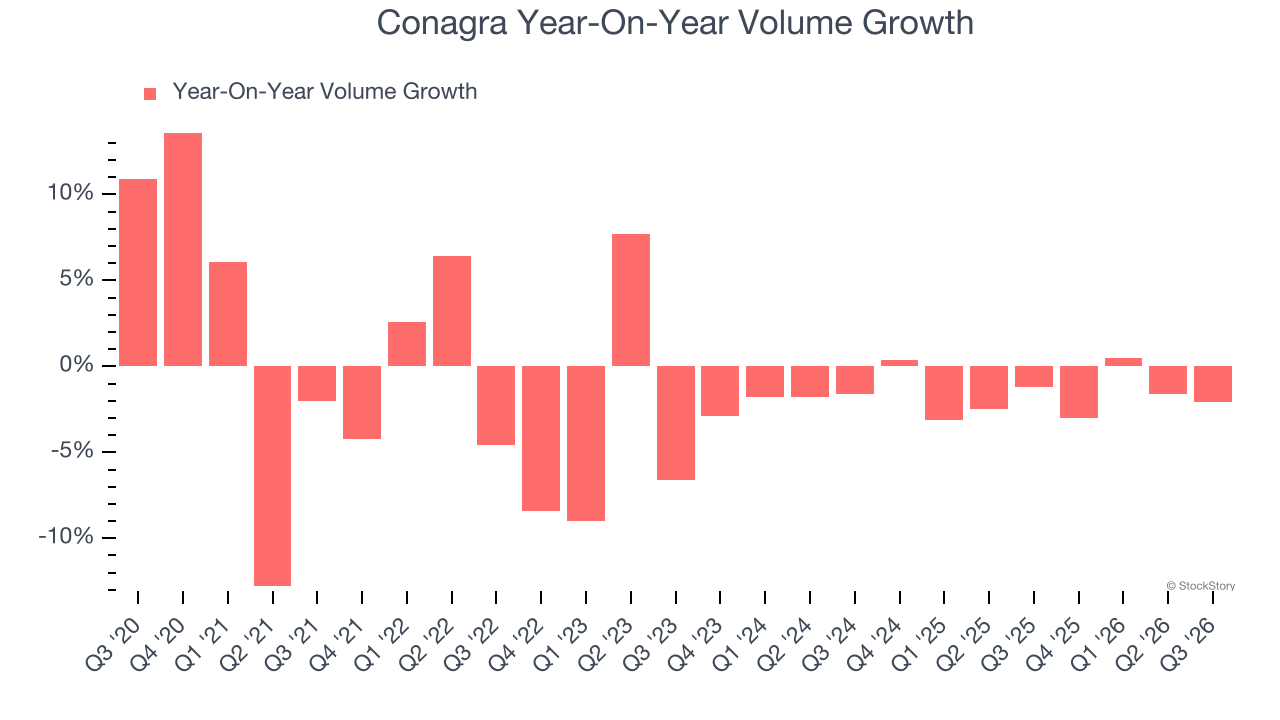
In Conagra’s Q3 2027, sales volumes dropped 2.1% year on year. This result represents a further deceleration from its historical levels, showing the business is struggling to move its products.
Key Takeaways from Conagra’s Q3 Results
It was good to see Conagra beat analysts’ EPS expectations this quarter. We were also excited its EBITDA outperformed Wall Street’s estimates by a wide margin. Overall, we think this was a decent quarter with some key metrics above expectations. The stock traded up 2.6% to $14.47 immediately following the results.
Sure, Conagra had a solid quarter, but if we look at the bigger picture, is this stock a buy? If you’re making that decision, you should consider the bigger picture of valuation, business qualities, as well as the latest earnings. We cover that in our actionable full research report which you can read here (it’s free).